What is the market overview and scope of the Produced Water Treatment Market?
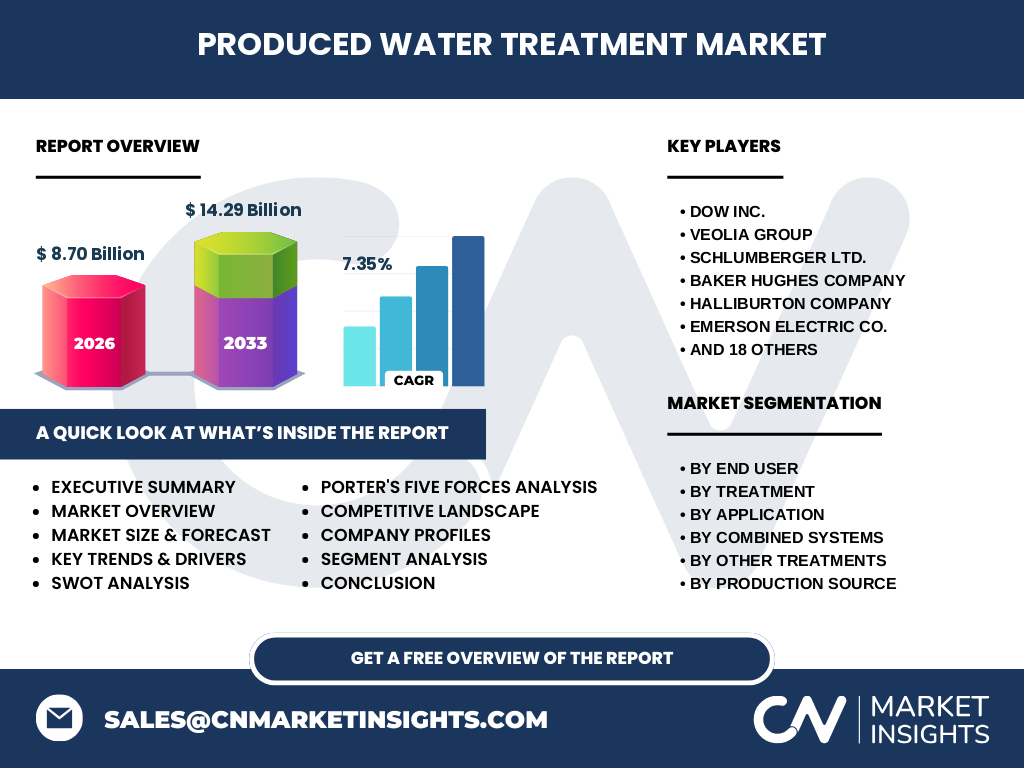
Our analysis indicates the Produced Water Treatment Market size stands at 8.70 Billion in 2026, driven by strict regulatory mandates from bodies like the EPA regarding hydrocarbon discharge. This sector encompasses chemical, biological, and membrane technologies deployed across crude oil and natural gas production sites to manage massive volumes of extracted formation water.
What are the key market drivers, restraints, challenges, and opportunities shaping the Produced Water Treatment Market?
Growth is propelled by rising water-to-oil ratios in mature fields and stringent zero-liquid discharge mandates. However, high capital expenditure for advanced oxidation processes and electrocoagulation acts as a restraint. Market opportunities lie in deploying combined systems like biological and chemical treatment to meet circular economy goals in arid operational zones.
Emerging trends and growth patterns in Produced Water Treatment Market
The shift toward decentralized reuse and smart digital monitoring is redefining the Produced Water Treatment Market industry trends. Operators are increasingly adopting advanced membrane technologies such as reverse osmosis and ultrafiltration to achieve potable-quality water standards right at the wellsite, minimizing trucking logistics and disposal costs.
How did COVID-19 impact the Produced Water Treatment Market and what does the recovery trajectory look like?
The pandemic caused widespread capital expenditure freezes and temporary drilling halts, depressing short-term demand. The recovery trajectory has since rebounded sharply, fueled by surging energy prices and accelerated adoption of automated chemical treatment and electrocoagulation systems designed to operate with leaner onsite workforces.
Competitive benchmarking and strategic dynamics in the Produced Water Treatment Market
Market concentration features a mix of oilfield services giants and specialized water technology leaders. Firms like Schlumberger Ltd. and Baker Hughes Company leverage integrated project delivery, while pure-play specialists such as Veolia Group and SUEZ Group deploy proprietary membrane and biological biofilm reactors to secure municipal-grade compliance contracts.
Executive Summary: High-level synthesis of key findings
Our comprehensive evaluation highlights a robust CAGR of 7.35% from 2027 to 2033, scaling the market from its 2026 baseline to 14.29 Billion by 2033. Stricter environmental liabilities and diminishing freshwater availability are forcing upstream operators to transition from disposal-heavy models to advanced onsite recycling loops.
Market forecast trajectory for the Produced Water Treatment Market from 2027 to 2033
Based on our research, the market will expand aggressively, reaching 14.29 Billion by 2033 at a 7.35% CAGR. This upward trajectory is anchored by offshore deepwater projects requiring compact skid-mounted separation units and onshore unconventional plays needing massive hydraulic fracturing flowback management.
Segmentation analysis of the Produced Water Treatment Market
The market is segmented by end user into oil and gas, industrial, power generation, and other end users. Treatment categories span chemical, reverse osmosis or membrane, biological, physical, and combined systems. Applications are divided into onshore and offshore, with production sources covering crude oil and natural gas extraction streams.
Regional market analysis and geographic distribution
Geographic performance is heavily influenced by regional environmental enforcement and mature basin maturity. North America leads in adoption due to intense shale gas activity requiring robust oil-water separation and filtration, whereas the Middle East prioritizes high-capacity reinjection systems to maintain reservoir pressure in aging mega-fields.
In-depth regional review of operational constraints and growth catalysts
North American operations face stringent local seismic disposal limits, accelerating demand for closed-loop recycling. Meanwhile, offshore operations in the North Sea navigate rigorous OSPAR Commission discharge limits, driving investments in advanced centrifugal separation and microfiltration technologies managed by specialized engineering firms.
Company profiles and strategic positioning of leading market participants
Industry leaders maintain distinct competitive moats. Dow Inc. and DuPont Inc. dominate the membrane chemistry space, while GE Water & Process Technologies and Aquatech International excel in engineered thermal treatment and turnkey evaporation systems tailored for zero-liquid discharge requirements.
Porter's Five Forces analysis of the Produced Water Treatment Market
Bargaining power of buyers is moderate to high, as E&P operators demand customized, cost-effective skids. Threat of substitutes remains low given strict statutory water quality limits. Competitive rivalry is intense, forcing established players like TechnipFMC plc. and National Oilwell Varco Inc. to innovate continuously in modular treatment architectures.
SWOT analysis: Strengths, weaknesses, opportunities, and threats
Strengths include proprietary membrane formulations and extensive global service footprints. Weaknesses involve high capital intensity and complex logistics. Opportunities stem from agricultural reuse projects, while threats include volatile commodity pricing cycles that abruptly curtail upstream capital spending budgets.
Value chain analysis from raw materials to end-users
The value chain originates with specialty chemical and polymer suppliers, flows through equipment fabricators and engineering contractors, and terminates with oil and gas operators. Integration across this chain—exemplified by firms like Tetra Technologies Inc.—ensures seamless fluid management from wellhead separation to final beneficial reuse.
Investment insights and high-potential areas for capital allocation
High-potential areas include electrochemical treatment and electrocoagulation start-ups that reduce chemical dependency. Investors should target modular, containerized systems that offer rapid deployment for remote onshore shale plays, minimizing site construction delays and lowering total cost of water ownership.
Conclusion and key takeaways for stakeholders
The Produced Water Treatment Market analysis demonstrates that regulatory compliance and water scarcity are permanent structural tailwinds. Reaching 14.29 Billion by 2033, the sector rewards firms that integrate digital automation with robust physical and membrane separation technologies.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by combining proprietary trade registry customs data, primary stakeholder interviews with C-suite executives at firms like Emerson Electric Co. and Ovivo, and secondary macroeconomic indicators from energy ministries and environmental protection agencies worldwide.
Scope of the report and coverage parameters
This report covers global revenue projections from 2027 to 2033 with a 2026 base year. Limitations include unforeseen geopolitical shifts impacting oilfield activity and sudden regulatory revisions in key producing jurisdictions, though our models incorporate extensive sensitivity analyses to mitigate these variables.
Recent developments, strategic partnerships, and product launches
Recent market activity features strategic joint ventures focused on digital twin integration and modular zero-liquid discharge deployments. Companies like Microvi Biotech Inc. and DAS Environmental Expert GMBH have launched bio-catalytic systems designed to slash energy consumption in high-salinity produced water remediation projects.